
Living paycheck to paycheck used to be my entire life. Three years ago, I stumbled across zero-based budgeting, and honestly, it changed everything.
Back then, I’d stand in the grocery aisle, debating if I could afford both eggs and gas. My income looked fine on paper, but my wallet told a different story.
Zero-based budgeting makes you give every dollar a job. You assign each dollar you earn to a category, so when you subtract expenses from income, you hit zero. That forces you to prioritize what matters and stop money from slipping through the cracks.
This method doesn’t make cheap living feel like punishment. Instead, it feels like I’m finally in control—and that’s empowering.

What I love about zero-based budgeting for frugal living is the built-in accountability. If I’ve already set aside $200 for groceries and $30 for dining out, I can’t just blow $40 on takeout because I feel lazy.
The first month I tried this, I found $300 hiding in my budget. Turns out, I was leaking cash on mindless convenience stuff and random impulse buys.
You’ll see how to set up this budget system step by step. We’ll dig into which categories save you the most money, and I’ll share a few tricks that help every dollar go further.
Whether your income is all over the place or you’re just tired of scraping by, zero-based budgeting gives you a framework to build stability, without living like a hermit.
Key Takeaways
- Zero-based budgeting assigns every dollar a purpose, so you avoid wasteful spending and boost your savings
- It works especially well for tight budgets because it forces you to choose essentials first
- To succeed, track your spending and tweak your categories every month to fit your real life
What Is Zero-Based Budgeting and Why It Works for Cheap Living

Zero-based budgeting is a budgeting method where you assign every dollar of your income to a category until you hit zero. This way, you plug the leaks and make your money work as hard as you do.
Key Principles of Zero-Based Budgeting
Zero-based budgeting is simple: Income – Expenses = Zero. You’re not just blindly spending. You’re telling your money where to go before the month even starts.
The budgeting process resets every month. You don’t just copy last month’s spending—every expense has to earn its place.
Here’s what you do:
- List your monthly income from all sources
- Write down fixed expenses like rent and utilities
- Plan variable costs like groceries and gas
- Allocate what’s left to savings and debt
- Assign every last dollar so nothing is left floating
This system makes you get intentional. If you bring in $2,800, you allocate exactly $2,800 across your categories. No freeloading dollars.
You cut out impulse spending because you can’t buy anything unless it’s already in the plan.
Zero-Based Budgeting vs. Other Methods

Traditional budgets usually just look at what you spent last month and go from there. Zero-based budgeting wipes the slate clean every time.
With traditional budgeting, you might just assume you’ll spend $400 on groceries again. But with zero-based budgeting, you ask, “Do I need $400 this month?” Maybe you need more, maybe less—depends on your actual plans.
| Traditional Budgeting | Zero-Based Budgeting |
|---|---|
| Uses past spending patterns | Starts fresh each month |
| Less detailed planning | Assigns every dollar |
| Money often unaccounted for | No leftover money |
| Reactive approach | Proactive planning |
Other methods, like the 50/30/20 rule, just use percentages. Zero-based budgeting uses real numbers. That helps you spot the tiny leaks that percentages miss.
Envelope budgeting is similar, but ZBB takes it a step further—every dollar gets a job before the month even starts.
Benefits of Zero-Based Budgeting for Frugal Lifestyles

Zero-based budgeting flips your money mindset. Instead of wondering where your paycheck disappeared to, you decide where every dollar goes.
You cut waste because you have to justify each expense. That $15 subscription you forgot about? It gets the axe.
You boost your savings because any money you don’t spend goes straight to your goals. If you skip a takeout meal, that cash lands in your emergency fund.
You stress less because you know exactly how much you can spend on groceries, guilt-free.
This approach helps you focus on what matters. If you’ve got $100 left, you get to choose: movie night or extra debt payment?
You build better money habits because every purchase has to pass the “does this fit the plan?” test.
If your income is unpredictable, you can still make this work. Just adjust your budget based on what you actually earn, not what you hope you’ll earn.
You might spot spending you didn’t even realize was happening. Maybe $200 a month on convenience foods? Yikes. Meal prep could cut that in half.
See Related: What Is Frugalism and How It Works Rules for Financial Freedom
Step-by-Step Guide to Setting Up a Zero-Based Budget

Making a zero-based budget means you tell every dollar where to go before you spend it. You’ll track your income, break down your expenses, and keep tweaking until your income minus expenses equals zero.
1. Listing All Sources of Monthly Income
Kick things off by figuring out your total monthly income. This is your budget’s backbone.
Write down what lands in your bank account after taxes. Ignore your gross salary—only count what you can use.
Add in side hustle money, freelance gigs, or anything you get regularly. If your income bounces around, use your lowest typical month just to be safe.
Other income to include:
- Child support
- Social Security
- Rental checks
- Dividends
- Unemployment
- Any other steady cash
So, if you pull in $3,200 a month, that’s your starting point.
2. Identifying and Categorizing Expenses

List out every expense you face in a typical month. Group them so tracking doesn’t make you want to scream.
Fixed expenses don’t change. Rent, mortgage, insurance, and minimum debt payments go here.
Variable expenses shift a bit, but you still need them. Groceries, gas, utilities, and your phone bill fall into this group.
Discretionary expenses cover the fun stuff. Entertainment, eating out, subscriptions, and little splurges. These are the easiest places to cut.
Set up a simple tracking system. Even a basic template works.
| Category | Type | Estimated Amount |
|---|---|---|
| Housing | Fixed | $1,200 |
| Groceries | Variable | $400 |
| Transportation | Variable | $250 |
| Entertainment | Discretionary | $150 |
Dig into your last three months of bank statements. You’ll probably spot expenses you forgot about.
3. Assigning Every Dollar a Job

Now comes the real work—giving every dollar a job. Take your income and break it up across your expense categories.
Start with fixed expenses. They’re easiest since they rarely change.
Next, set aside money for variable stuff like groceries and gas. Look at your history, but round up a touch so you don’t run short.
Don’t skip these:
- Emergency fund
- Extra debt payments
- Savings for goals
- Irregular stuff (car repairs, gifts)
Assign real numbers, not guesses. Your budget needs specifics to work.
If you have cash left over, don’t just let it sit. Toss it at debt or savings.
4. Checking That Income Minus Expenses Equals Zero

Time for the moment of truth. Add up all your expenses and subtract from your income—do you hit zero?
If you end up positive, you still have money to assign. Maybe boost your emergency fund or pay off more debt.
If you go negative, something’s gotta give. Cut back on wants first—entertainment, eating out, whatever you can live without.
People often:
- Trim the grocery bill with meal planning
- Cancel unused subscriptions
- Slash entertainment
- Shop around for cheaper insurance
Keep tinkering until the numbers line up. It might take a few rounds, especially at first.
A simple spreadsheet or digital tool can save you headaches. Honestly, most folks find apps easier than paper.
Don’t expect your first budget to be perfect. You’ll need to adjust as you get a feel for your real spending.
Finding and Prioritizing Budget Categories That Cut Costs

Zero-based budgeting is all about telling your money what to do before it disappears. The trick is to sort your expenses by what you need to survive and what can wait.
5. Essential Expenses: Rent, Food, and Utilities

Essentials come first. These are your fixed expenses—the stuff you can’t live without.
Housing should eat up no more than 30% of your take-home pay. If it’s higher, you might want to consider a roommate or moving somewhere cheaper.
Your monthly bills—electricity, water, gas—are non-negotiable, but you can still trim them. Try setting the thermostat a bit lower in winter or unplugging electronics.
Groceries are essential, but eating out isn’t. Plan meals around what’s on sale or in season. With some effort, a family of four can eat well on $600 a month.
If you own your home, don’t forget about property taxes. Break up the yearly bill so you’re not caught off guard.
6. Avoiding Overspending on Discretionary Categories

Discretionary expenses are where budgets go to die if you don’t watch out. Clothes—plan for them.
Set aside $50-100 a month and stick to it. Shop your closet before you hit the mall.
Entertainment and eating out are nice, but not essential. Limit restaurant trips to once a week. Look for free fun—hiking, library events, whatever you enjoy.
Subscriptions can sneak up on you. Cancel anything you don’t use every week. One family I know saved $180 a month by keeping just Netflix.
Set a “fun money” cap. When it’s gone, stop spending on wants until next month. It’s not glamorous, but it works.
7. How to Budget for Irregular and Seasonal Expenses

Irregular expenses sneak up on us and can blow up an otherwise solid budget. But honestly, most of them aren’t that mysterious if you take a step back and plan.
For example, car insurance usually pops up every six months. Car payments might hit monthly, but stuff like maintenance and registration? That’s a whole different timeline. I like to stash $100 each month for repairs and $20 for those annoying registration fees.
Seasonal expenses—think holiday gifts, back-to-school shopping, summer camps—deserve their categories. If you start saving in January for December gifts, you’ll thank yourself later.
Childcare costs can skyrocket during school breaks. It’s so easy to forget about spring break camps or summer programs until you’re scrambling.
So, what works?
- List every irregular bill you paid last year.
- Add up the total.
- Divide by 12 to find your monthly savings target.
- Make separate budget categories for each.
A maintenance fund is a lifesaver. I set aside $50 a month for home repairs and another $100 for those “oh no” medical bills.
Adapting Zero-Based Budgeting to Irregular or Low Incomes

Variable income can mess with your budgeting goals, but it doesn’t have to. Building emergency funds and using side hustle earnings takes a bit of strategy, especially when your income’s all over the place.
Budgeting Strategies for Variable Income

I always start with my lowest monthly income from the past year—let’s say you earned anywhere from $1,800 to $3,200. Use $1,800 as your baseline.
Make two budgets: your survival budget (just the essentials like rent, utilities, groceries, minimum debt payments) and your opportunity budget (for when you get a little breathing room).
Try the envelope method for variable expenses. Put $200 in cash for groceries, $100 for gas, $50 for entertainment. When the envelope’s empty, you’re done. Simple, but effective.
| Income Level | Fixed Expenses | Variable Expenses | Extra Money |
|---|---|---|---|
| $1,800 (minimum) | $1,200 | $400 | $200 |
| $2,500 (good month) | $1,200 | $400 | $900 |
| $3,200 (great month) | $1,200 | $400 | $1,600 |
Track your income for three months. You’ll spot patterns—maybe you always earn more in the summer, or January is a slow month.
Building Buffers for Unexpected Expenses

Your emergency fund isn’t optional when your income’s unpredictable. Shoot for three to six months of your baseline budget, not your best month ever.
If you’re living paycheck to paycheck, start with $500. Add $25 from every paycheck until you hit $1,000.
Set up sinking funds for those predictable, but irregular, expenses. I put $30 a month toward car repairs, $20 for medical stuff, $15 for home maintenance.
Use separate savings accounts for different things—one for emergencies, another for sinking funds, and a third for “opportunity money” when you get a windfall.
When you have a good month, don’t let lifestyle creep eat your progress. Throw 70% of that extra cash at your emergency fund and sinking funds before you even think about spending more.
Side Hustle Income and Additional Earnings

Treat side hustle money as a bonus until you’ve earned it consistently for six months. Don’t count on it to cover your basics right away.
Trackside hustle income on its own. I use a simple spreadsheet with columns for date, source, amount, and whether it’s one-time or recurring.
Split side hustle money using the 50/30/20 rule: 50% goes straight to your emergency fund, 30% to debt or savings goals, and 20% is yours to enjoy.
Seasonal side hustles like tax prep or holiday retail can be a game-changer. Plan these out six months ahead and assign the money to a specific goal.
Think about how steady your side gig is. Freelance writing can be feast or famine, but dog walking? That’s often more reliable.
Tools and Resources to Make Zero-Based Budgeting Easier

Having the right tools can make zero-based budgeting feel less like a chore. Whether you’re into apps, cash envelopes, or old-school spreadsheets, find a system that works for you.
Choosing a Budget App or Spreadsheet

YNAB (You Need a Budget) is the classic zero-based budgeting app. It’s $14.99/month, but it forces you to decide where every dollar goes. It links to your bank accounts and shows exactly where your money’s going.
EveryDollar has a free version that’s great for basics. You enter everything by hand, which—honestly—keeps you more aware of your spending. If you want bank connections, it’s $17.99/month.
If you love spreadsheets, Tiller is $6.58/month and pulls your transactions into Google Sheets or Excel automatically. You get a ton of control and still benefit from automation.
You can always use free spreadsheet templates in Google Sheets or Excel. I know plenty of folks who use a simple three-column setup: income, expenses, and what’s left. The trick is to pick a tool you’ll stick with.
Mint is gone now, but other free apps like PocketGuard can help you track spending. Just know that most don’t do real zero-based budgeting.
Using Cash Envelope and Hybrid Systems
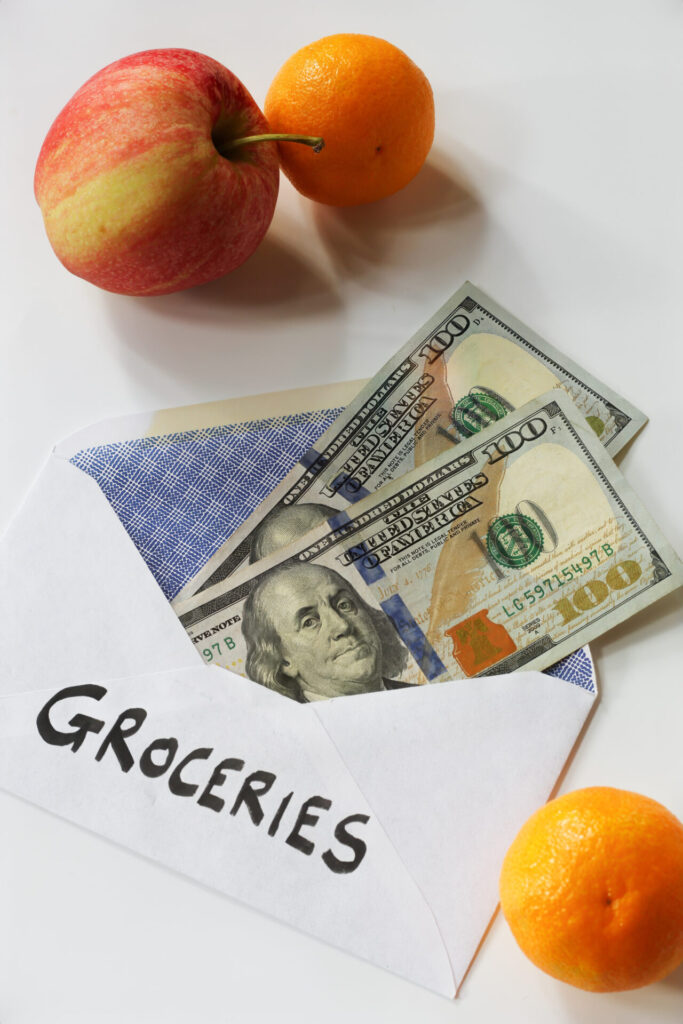
Cash envelopes are old-school but super effective. Make envelopes for groceries, entertainment, whatever you tend to overspend on. When the money’s gone, you’re done.
Start with just a couple of categories—groceries and dining out, maybe. I’d put $400 in groceries, $100 in dining out. You’ll see your limits, and that’s a good thing.
Hybrid systems mix digital and cash. Use your app for planning, but pull cash for those categories where you always blow the budget. Keep the boring stuff (rent, utilities) on autopay.
Lots of people use cash for groceries, gas, and fun money, and keep the rest digital. You get control of cash without juggling envelopes for every single thing.
The envelope system is also great for families. Kids can see exactly how much is left for different activities, which makes those “can we?” conversations way easier.
Customizing a Budget Template for Your Needs

Budget templates can save you hours, but you’ve gotta tweak them for your real life. Start with a basic monthly budget template and plug in your actual income and expenses.
Add categories that fit your cheap living style. If you meal prep, make a “meal prep supplies” category. Love free stuff? Track “free activities” so you can see those wins.
Budget worksheets should match your pay schedule. If you get paid weekly, break your monthly budget into weeks. That way, you don’t blow half your money in the first week.
Include a “budget buffer” of $50-100 for those little surprises. It’ll keep your budget from falling apart when life gets weird.
Online budget calculators can help you figure out what’s realistic for each category. Use them to get ballpark numbers, then cut them down if you’re all about cheap living.
Track your “cost per use” for anything over $25. Just add a column to your spreadsheet and divide the cost by how many times you’ve used it. It’s nerdy, but it’ll help you spend smarter next month.
See Related: Frugal vs Cheap Differences That Can Transform Your Financial Life While Maintaining Quality
Frugal Strategies: Maximizing Savings While Living Cheap

When you live frugally with zero-based budgeting, every dollar gets a job—saving, paying down debt, or covering the stuff you know is coming. It’s all about setting savings goals, knocking out debt, and preparing for life’s curveballs with sinking funds.
Setting and Achieving Savings Goals on a Tight Budget

Your savings goals should be clear and doable, especially if money’s tight. Instead of “save more,” try “save $25 per month for three months.” That’s something you can hit.
Start with micro-savings goals. Even $5 a week adds up to $260 a year. Once that feels easy, bump it to $10 a week.
Open separate savings accounts for different goals. Most banks let you open as many as you want for free, so use one for emergencies and another for your next vacation.
Track your progress visually. Use a chart or an app to watch your balance grow. It’s weirdly motivating to see your emergency fund go from $50 to $100 to $200.
Think about both short-term and long-term goals:
- Short-term: $500 emergency fund, new coat, car oil change
- Long-term: House down payment, retirement, kids’ college
Automate your savings. Set up a $20 transfer right after payday. If you never see it, you won’t spend it.
Tackling Debt and Building an Emergency Fund

You’re stuck between paying off debt and building an emergency fund, right? The answer is both, but in a smart order.
Start with a $1,000 emergency fund before you go hard at debt. That way, surprise expenses don’t send you running back to your credit card.
Try the debt snowball method for a quick win. List your debts from smallest to biggest—forget interest rates for now. Pay minimums on everything but the smallest debt, and throw every extra dollar at that one.
Here’s a quick example:
- Credit card: $500 (min $25)
- Student loans: $8,000 (min $150)
- Car loan: $12,000 (min $280)
Focus on that $500 credit card until it’s gone. Then, add that $25 to your student loan payment.
Debt payments should always be a fixed part of your zero-based budget. Treat them like rent or utilities—non-negotiable.
After you’re debt-free, roll those payments into your emergency fund. If your monthly expenses are $2,000, build up $6,000–$12,000 for real peace of mind.
Planning with Sinking Funds for Big or Irregular Expenses

Sinking funds are the unsung heroes of budgeting. These are mini-savings buckets for stuff you know is coming, just not every month.
Common sinking fund categories:
- Car repairs ($50/month)
- Gifts for holidays and birthdays ($40/month)
- Home maintenance ($75/month)
- Clothes ($30/month)
- Annual subscriptions ($20/month)
Start small if you have to. Even $10 a month for Christmas means you’ll have $120 for gifts by December.
Treat sinking fund contributions as regular expenses in your zero-based budget. They’re just as important as your electric bill.
Open separate savings accounts or budget categories for each sinking fund. This stops you from “borrowing” from your car fund to buy Christmas presents.
Figure out how much you need by checking last year’s bills. If car repairs cost $600, save $50 a month. If Christmas ran you $300, put away $25 monthly.
Finding Balance: Fun Money and Giving on a Budget

Cheap living doesn’t mean you never have fun. Your budget should leave a little room for fun money and giving, even if it’s not much.
Fun money is guilt-free. Maybe it’s $20 a month for coffee or $15 for a movie. The amount isn’t the point; having it is.
If you’re partnered, split fun money down the middle. Each person gets their stash, no questions asked. It stops arguments over “silly” spending.
Giving is possible, even on a shoestring:
- $10 a month to your favorite charity
- Volunteer instead of donating cash
- Chip in to a friend’s fundraiser when you can
Your money goals should always include a little joy and some generosity. When you hit a savings milestone, treat yourself with a small splurge from your fun money.
Balance matters. If you make your budget too strict, you’ll snap and overspend. Build in a little fun and giving, so you can stick with it.
Change things up by season. Maybe you want more fun money in summer for outdoor stuff, less in winter when you’re hibernating. That’s fine.
Common Mistakes and How to Stick With Your Zero-Based Budget

Even the most dedicated budgeters hit snags with their zero-based budget, whether it’s forgetting to track a quick coffee run or getting blindsided by a surprise bill. Building habits around monthly reviews and staying flexible matter when life throws you a curveball.
Tracking and Adjusting Monthly Spending

People mess up when they treat their budget like a crockpot—set it and walk away. Zero-based budgeting needs your attention, honestly, almost daily.
Track expenses right away. Seriously, grab your phone and log that $3 coffee the moment you buy it. If you wait, you’ll just end up asking yourself, “Where did all my cash go?”
I like setting up weekly check-ins every Sunday. Just take a look at what you spent versus what you planned. If you blew $180 on groceries when you meant to spend $150, something’s gotta give elsewhere.
Add a $50 “oops fund” to your monthly budget. That little buffer lets you move cash around without blowing up your whole system.
After three months, look at your spending patterns. Maybe you’re always over on gas but under on takeout. Adjust those categories so your budget fits your life.
Think of budgeting like brushing your teeth—just something you do every day, no big deal, but pretty important.
Handling Unexpected Changes Without Losing Momentum

Life happens. You can’t predict every flat tire or doctor visit, but you can plan for the unexpected.
Build sinking funds right into your budget. Set aside $25 a month for car repairs, $30 for medical stuff, $20 for home fixes. It’s not glamorous, but it saves you from panic mode.
When a surprise expense pops up, don’t throw your budget out the window. Open up your plan and shuffle the numbers. Maybe you cut $100 from restaurants to cover that car repair.
Next month? Adjust your budget based on what just happened. If you had three emergencies, maybe your emergency fund needs a little more love.
Keep things flexible. Your budget should fit your real life, not the other way around. Get a bonus at work? Give every extra dollar a job right away.
Overspend in one category? That’s not a fail. Just means you’ll have to tighten up somewhere else to keep the budget balanced.
Reviewing Progress and Refining Your Frugal System

Most folks skip the review step, but honestly, that’s where the magic is. Each month, your budget should get a bit sharper as you learn.
Set up monthly budget meetings with yourself. Check what worked and what flopped. If groceries are always over, maybe you lowballed your estimate.
Celebrate your biggest money wins each month. Maybe you saved $200 by meal planning or switched to a cheaper phone plan. Those victories keep you going.
Try a simple scoring system:
- Green: Stayed within budget
- Yellow: Over by less than 10%
- Red: Over by more than 10%
If a category is always red, bump up the budget or figure out how to cut costs there.
Let your budget evolve as your life does. Got a raise? Assign those extra dollars. Do kids start school? Shift your categories to match.
You’re not aiming for perfection—just progress. Every month should feel a little easier than the last.
See Related: How to Be Frugal Without Seeming Cheap Smart Habits for Big Wins
Frequently Asked Questions

Zero-based budgeting always sparks questions about how to start, which tools to use, or if it’s even worth the effort for frugal folks. Here are some practical answers about expense minimization, creating a budget, and dealing with the usual headaches.
How can I effectively implement zero-based budgeting to minimize my expenses?
Start by tracking every expense for two weeks. Write down every single purchase, even that $1 pack of gum. Just seeing where your money goes can cut spending by 10-15%.
Build spending categories based on what you actually need. Housing, utilities, food, transportation—those are non-negotiable. Everything else? Question it. That $15 streaming service you barely use? Ditch it.
Justify every dollar. Before you put money in any category, ask, “Does this help me reach my financial goals?” If not, send that cash to savings or debt.
Set up automatic transfers to savings right after payday. Out of sight, out of mind. Even $50 a month adds up.
During your first month, review your budget every week. If you planned $200 for groceries but spent $250, either up the grocery budget or cut somewhere else.
What are the practical steps to creating a zero-based budget for a frugal lifestyle?
Figure out your exact monthly take-home pay. Count your main job, side hustles, all of it. If your income changes, use your lowest month as your baseline.
List all your fixed expenses first—rent, insurance, minimum debt, utilities. Usually, these take up 50-60% of your income.
Estimate your variable expenses by checking the last three months of bank statements. Look at what you spend on groceries, gas, and personal care. Try to trim 10% off your current average, but don’t get too wild.
Before spending on extras, allocate money for savings goals. Emergency fund, retirement, debt—those come before eating out or buying new shoes.
Give every leftover dollar a job. If you’ve got $100 left, decide exactly where it goes. Maybe $50 for fun, $50 for random stuff.
Test your budget for a month. Track every expense. Expect to tweak things as you learn what works for you.
Could you explain the pros and cons of zero-based budgeting for someone trying to live economically?
Zero-based budgeting makes you look at every expense, and honestly, you’ll probably find $200-500 a month in waste to redirect toward savings or debt.
You call the shots with your money. No more “Where did my paycheck go?”—you tell every dollar what to do.
This method stops lifestyle creep in its tracks. Get a raise? You decide where the extra cash goes, not your impulses.
But it takes time. Plan on spending 2-3 hours a month at first, just getting your system dialed in.
It can feel restrictive, especially if you’re used to winging it. Sticking to spending limits is a real adjustment.
The monthly planning gets repetitive. Unlike set-and-forget budgets, you have to actually plan each month.
Some people just don’t like the nitty-gritty tracking. If you want super-simple, zero-based budgeting might feel like overkill.
What are some helpful tools or templates for setting up a zero-based budget?
YNAB (You Need A Budget) is built for zero-based budgeting. It’s $14.99 a month, but it forces you to give every dollar a job. Most people save more than the cost in their first month.
EveryDollar is free and lets you do zero-based budgeting too. You have to enter transactions by hand, but honestly, that keeps you more aware.
Google Sheets has free templates—just search “zero-based budget template.” Spreadsheets give you full control, and you can tweak categories as much as you want.
Mint offers zero-based features in its free platform. It categorizes transactions automatically, though you’ll need to make sure every dollar gets assigned.
If you’re into cash, try the envelope system. Pull out your budgeted cash and put it in labeled envelopes for each category.
Or just grab a notebook. Make columns for income, expenses, and what’s left. Update it daily if you want to stay on track.
How does the zero-based budgeting approach compare to the 50/20/30 budgeting rule?
The 50/20/30 rule splits your money—50% for needs, 20% for savings, 30% for wants. It’s straightforward, but you don’t have to plan every dollar.
Zero-based budgeting makes you get specific. You break things down to groceries, utilities, and entertainment—every dollar has a job.
If you want something simple, the 50/20/30 rule works. You can ballpark your expenses and adjust as you go.
Zero-based budgeting gives you more control and awareness. You know exactly where your money’s going, and you’ll probably waste less.
For frugal living, zero-based budgeting usually wins. When you dig into the details, it’s way easier to spot places to save.
The 50/20/30 rule can be too loose if you’re trying to save aggressively. Spending 30% on wants might slow down your debt payoff or savings.
Think about what fits your style. If you like details and control, go zero-based. If you want simplicity, try 50/20/30 and see how it feels.
What challenges might I face with zero-based budgeting, and how can I overcome them?
Honestly, most people hit a wall with budget planning after a couple of months. I get it—it gets old. Try batching similar expenses together, or whip up a few templates for those bills that just keep coming back every month.
Then there are those sneaky, irregular expenses. Car repairs, birthday gifts, holiday stuff—they show up like clockwork, but never when you want them. I like to set up little sinking funds, just tossing aside a bit each month so I’m not blindsided.
Overspending in one category? It happens to everyone. Don’t throw out your whole plan—just shuffle things around. Maybe pull a little from your entertainment fund if you went over on groceries. No shame in that game.
If your income bounces up and down, zero-based budgeting can feel like juggling flaming swords. I usually pick my lowest monthly income as the starting point. Anything extra, I toss at savings or debt.
Getting the whole family on board? That’s another beast. Some folks hate tracking every penny. I’d say start with the big stuff—groceries, rent, whatever—and let everyone ease into the details over time.
Oh, and perfectionism? It’s a trap. Your first budget won’t be perfect. Mine wasn’t either. Just get started and tweak as you go. Progress beats perfection every single time.
Leave a Reply