Trying to figure out how long it’ll take to double your money really matters—especially if you’re planning for retirement, saving for a down payment, or just deciding where to stash your emergency fund. The rule of 72 and the rule of 70 are classic shortcuts for estimating the magic “doubling time” without reaching for a fancy calculator.
Here’s the gist: the rule of 72 has you divide 72 by your annual return rate, while the rule of 70 uses—you guessed it—70. The rule of 72 usually nails it for most investment returns between 6% and 10%. It’s just a hair more accurate in that range.
Let’s walk through when each rule actually works best, how to pick the right one for your money goals, and a few missteps that can throw off your estimates. I’ll keep it simple—no jargon, just the straightforward math you need to make smarter decisions.
Key Takeaways
- The rule of 72 is a bit more accurate for most investment returns, but the rule of 70 shines with lower growth rates
- Both rules let you estimate doubling time by dividing the rule number by your annual return percentage
- Knowing when to use which rule helps you set real expectations for your savings and investments
What Is the Rule of 72?
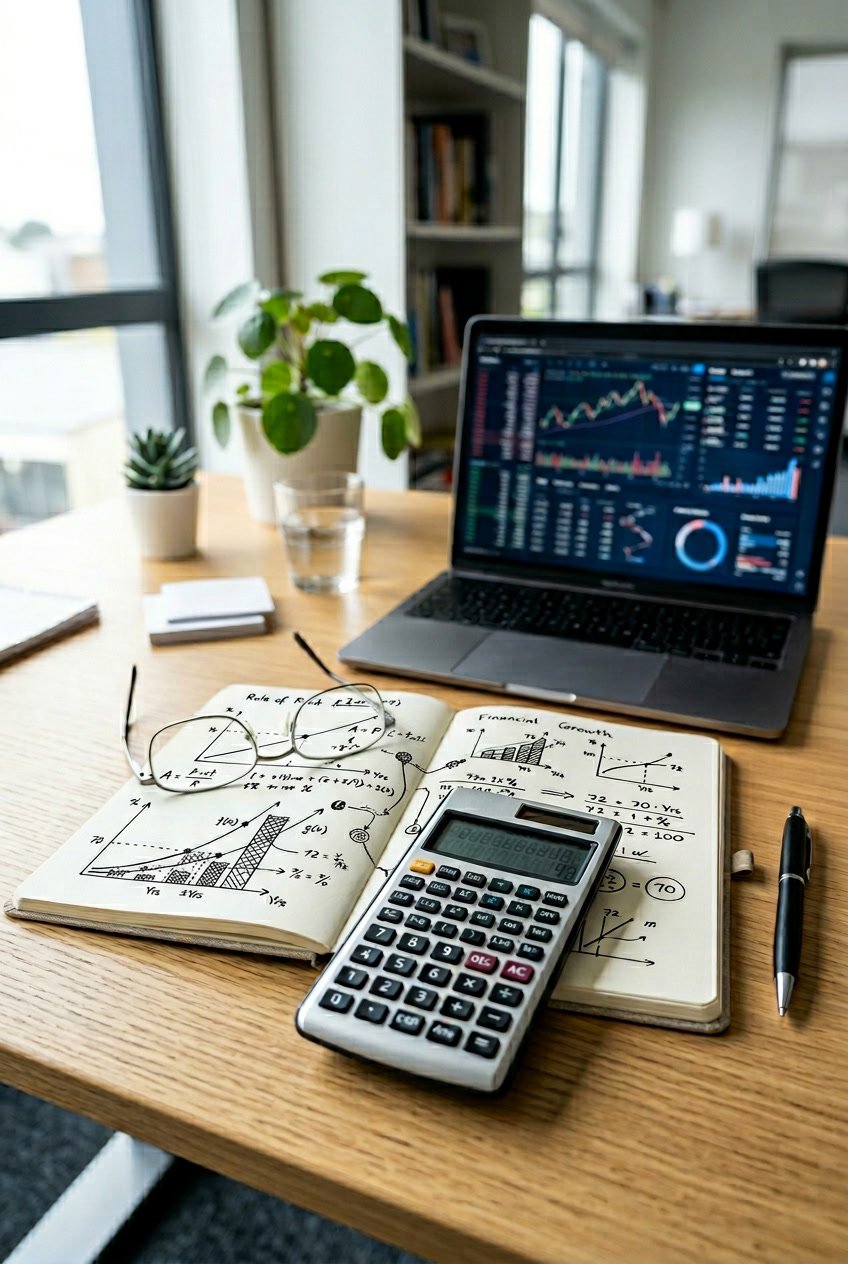
The Rule of 72 is basically a mental shortcut for figuring out how many years it’ll take your money to double at a certain annual return. You just divide 72 by your interest rate, and—boom—you’ve got a ballpark answer for when your investment will double from compounding.
How to Calculate Using the Rule of 72

Grab the number 72 and split it by your expected annual return. That’s your rough doubling time.
Let’s say you’re earning 6% on a savings account. Divide 72 by 6 and you get 12. So, your $5,000 would become about $10,000 in 12 years, even if you don’t add another cent.
You can flip the formula, too. If you want to double your money in 9 years, divide 72 by 9. You’ll need an 8% annual return to make that happen.
Here’s a quick table for different rates:
| Annual Rate of Return | Years to Double (72 ÷ Rate) |
|---|---|
| 3% | 24 years |
| 6% | 12 years |
| 8% | 9 years |
| 10% | 7.2 years |
| 12% | 6 years |
You don’t even need a calculator for this. It’s the kind of math you can do while sitting at your kitchen table, weighing investment options.
When the Rule of 72 Is Most Accurate

You’ll get the best results from the Rule of 72 if your return falls between 6% and 10%. That covers most index funds, balanced portfolios, and the S&P 500’s long-run average.
In that sweet spot, the estimate is usually off by just a few months. For long-term planning, that’s close enough.
Once you wander outside that range, accuracy drops. At 2% or 3%, the Rule of 72 overstates how fast your money grows. Go up to 15% or 20%, and it underestimates.
For rates under 5%, the Rule of 70 actually edges out 72 in precision. But honestly, most folks stick with 72 because it’s easier to divide in your head. 72 just has more factors—1, 2, 3, 4, 6, 8, 9, 12, 18, 24, 36, 72—so you don’t get stuck with awkward decimals.
This rule assumes your interest rate stays the same and compounds every year. Real life isn’t that neat, but for average returns over decades, it works well enough.
Common Uses in Personal Finance

I use the Rule of 72 all the time to sanity-check retirement accounts. If your 401(k) earned 7% last year, you know it’ll roughly double every 10.3 years. That’s a heck of a lot easier than running endless projections.
It’s also handy for comparing investments. A bond fund at 4% doubles in 18 years.
A stock index fund at 9% doubles in 8 years. You can see the difference in growth right away, which helps you decide how much risk you’re up for.
You’ll also spot when fees eat into your returns. If a fund charges 1.5% and the market returns 8%, you’re really getting 6.5%.
Now your money doubles in 11 years instead of 9. Those two years can make a big difference when you’re building wealth.
The Rule of 72 can show you why paying off high-interest debt is usually smarter than investing. Credit card debt at 18%? You’re doubling what you owe every 4 years if you only pay the minimums. No investment reliably pays 18%, so wiping out that debt is a top priority.
What Is the Rule of 70?
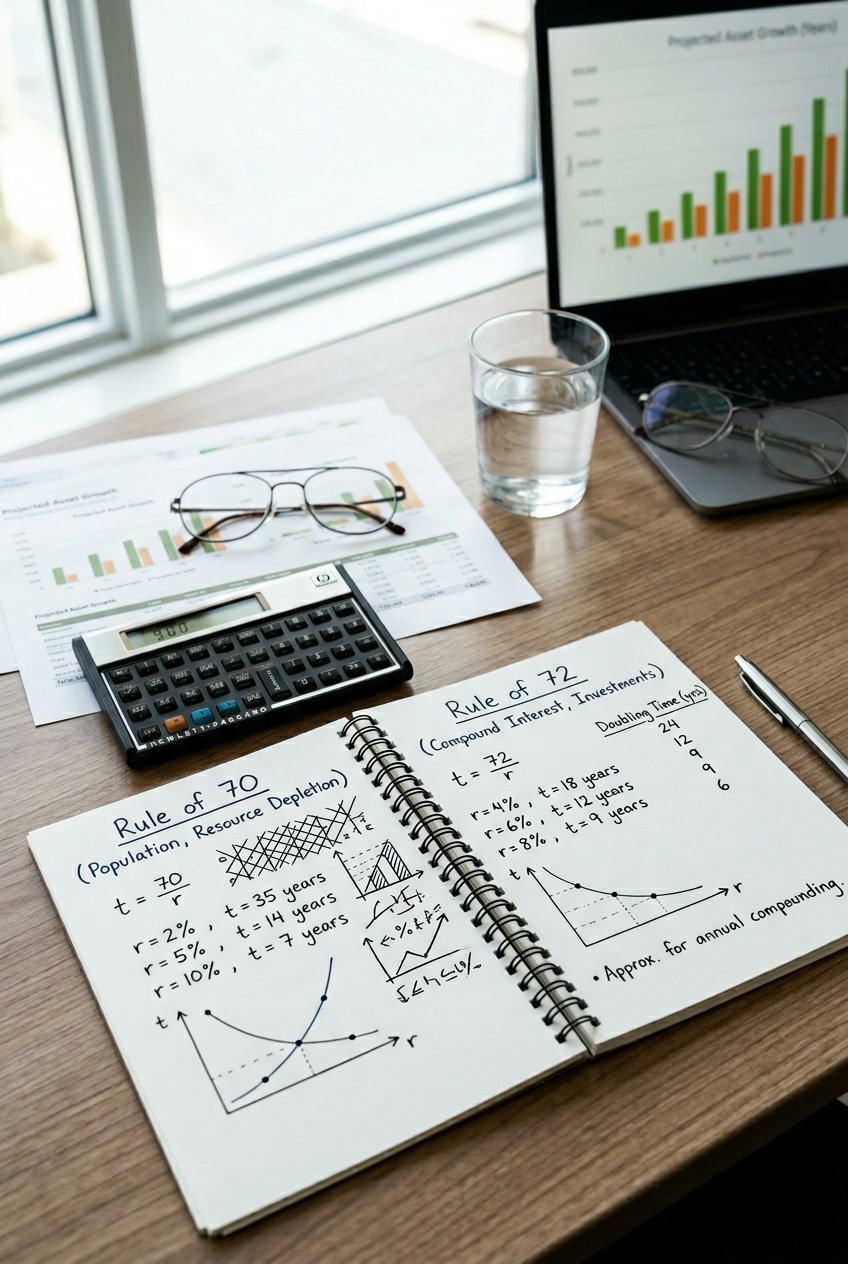
The rule of 70 is another quick trick for estimating how long it’ll take your money to double—just divide 70 by your annual growth rate. This one’s especially useful for investments with lower growth rates or when you’re crunching numbers for economic growth.
How to Calculate Using the Rule of 70

Divide 70 by your expected annual growth rate. If your investment earns 7% per year, 70 divided by 7 gets you 10 years.
Here’s the formula: Doubling Time = 70 ÷ Growth Rate
Let’s say your $5,000 in a bond fund earns 5% each year. It’ll take around 14 years to reach $10,000 (70 ÷ 5 = 14). If you’ve got $15,000 in a CD at 3.5%, you’re looking at 20 years to double (70 ÷ 3.5 = 20).
You don’t need to pull out a calculator for most of these. If your retirement account is growing at 8%, 70 ÷ 8 is about 8.75 years. This kind of quick math is great for comparing options or planning long-term savings.
The catch? The rule assumes your rate stays fixed. If rates jump around, your results will too.
Scenarios Where the Rule of 70 Shines

You’ll get the most accurate answers with rates below 10%. That makes the rule of 70 perfect for conservative stuff—treasury bonds, high-yield savings accounts, or steady dividend stocks.
It’s great for:
- Retirement savings earning 4-8%
- Municipal bonds with fixed returns (3-6%)
- GDP growth (usually 2-4% in developed countries)
- Population growth
- Certificate of deposit planning
Even mortgage planning can benefit. If home values in your area climb 4% a year, you can estimate doubling time without any spreadsheets.
Economists use this rule to estimate GDP doubling time. If a country’s GDP grows 3.5% a year, it’ll double every 20 years (70 ÷ 3.5).
I reach for the rule of 70 instead of 72 when I’m dealing with continuous compounding or when I just need a fast, rough answer. It’s quick and simple—perfect for those “back of the envelope” moments.
Limitations of the Rule of 70

Your estimates start to wobble if growth rates go above 10%. At 15% returns, the rule of 70 says you’ll double your money in 4.67 years, but the actual answer is closer to 5 years.
The rule assumes steady growth, but real life is messy. Maybe your portfolio returns 12% one year and loses 5% the next. Market swings make any doubling estimate pretty rough.
Taxes can mess with your math, too. If you’re in a 22% bracket and earn 6% in a taxable account, your after-tax return is closer to 4.7%. That stretches your doubling time from about 12 years to 15.
Inflation eats into your gains as well. If you earn 5% but inflation is 3%, your real growth is just 2%. Your money might double in 14 years on paper, but your actual purchasing power won’t.
The rule totally breaks down with negative growth or returns above 20%. For those cases, you’ll need the real compound interest formula—no shortcuts.
Rule of 72 vs Rule of 70: Key Differences
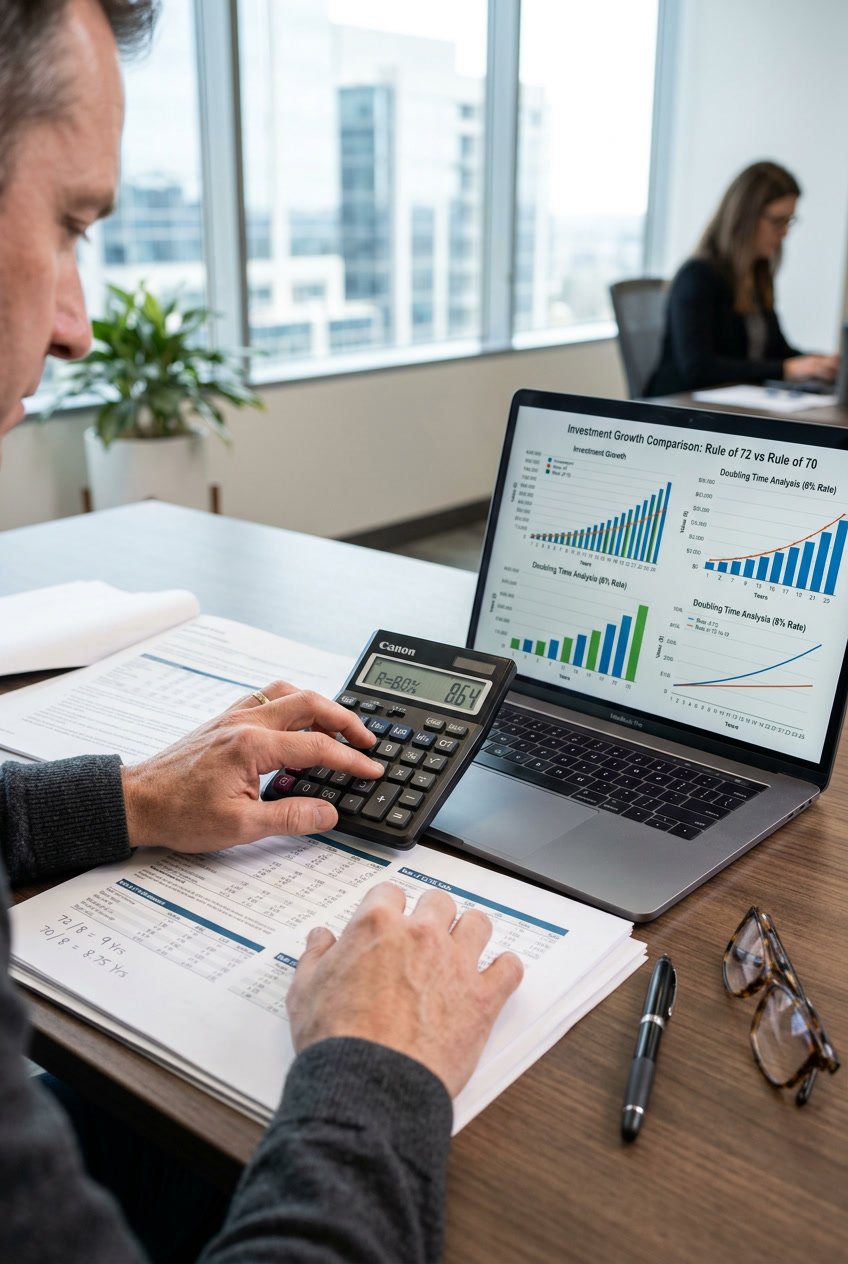
Both rules use simple division to estimate doubling time, but the number you divide by changes the precision. The rule of 72 divides 72 by your rate of return, while the rule of 70 uses 70. That small difference tweaks how quickly your money’s supposed to double.
Comparison of Calculation Methods

The rule of 70 says to divide 70 by your annual growth rate. If you’re earning 8%, 70 ÷ 8 = 8.75 years to
double.
The rule of 72 works the same way, just using 72 instead. At 8%, 72 ÷ 8 = 9 years. So, you get about a three-month difference.
Neither rule needs a calculator or any special tool. You can do the math in your head, even while waiting in line at the grocery store. The real doubling time formula is ln(2) ÷ ln(1 + r), with r as your decimal return, but who wants to mess with logarithms for a quick decision?
Accuracy and Real-World Examples
When interest rates are between 6% and 10%, the rule of 72 usually wins for accuracy. Invest $5,000 at 6%—the rule of 72 gets you 12 years (72 ÷ 6), and the rule of 70 says 11.67 years (70 ÷ 6). The real answer is 11.9 years, so 72 is closer.
If you go higher, the gap gets a bit bigger. At 12%, the rule of 72 says 6 years, the rule of 70 says 5.83 years, and the actual answer is 6.12 years.
For things like population growth or inflation, the rule of 70 does better. If inflation runs 3.5%, 70 ÷ 3.5 gives you 20 years—almost spot-on for continuous compounding.
Divisibility and Ease of Use

The number 72 just divides more easily by common rates—1, 2, 3, 4, 6, 8, 9, and 12—so you don’t get stuck with decimals as often.
That’s handy if you’re looking at index funds averaging 10% (72 ÷ 10 = 7.2 years) or savings at 4% (72 ÷ 4 = 18 years). 70 only divides cleanly by 1, 2, 5, 7, 10, 14, and 35.
If you’re earning 7% in a Roth IRA, the rule of 70 gives you a perfect 10 years. The rule of 72 gets you 10.29 years, so you’ll need to round.
For rates like 5%, 14%, or 7%, the rule of 70 gives you cleaner numbers. Pick your rule based on your rate—not just what sounds familiar.
See Related: Extreme Frugal Living Experiment Results Discover the Life-Changing Impact of True Frugality
When to Use Each Rule for Financial Planning
You can use both rules for quick estimates, but which one you pick really depends on the type of growth and how exact you want your answer to be. The rule of 72 usually works better for investments with compounded interest, while the rule of 70 feels a bit easier for continuous compounding or if you want to do some mental math on the fly.
Choosing Based on Investment Growth Rate
The rule of 72 hits the mark when your annual growth rate sits between 6% and 10%. That range covers most stock investments, mutual funds, and balanced portfolios.
Say you invest in an index fund averaging 8% a year. Divide 72 by 8, and you get 9 years for your money to double.
The rule of 70 gives you 8.75 years, which sounds more exact but isn’t as accurate for this rate.
If your growth rate drops below 5% or jumps above 12%, neither rule nails it. A high-yield savings account at 4%? You’ll want a calculator or spreadsheet. Same goes for those aggressive growth stocks promising 15% returns—don’t trust a shortcut there.
The rule of 72 is just easier to use in your head since 72 divides cleanly by lots of numbers (1, 2, 3, 4, 6, 8, 9, 12). At your advisor’s office or while checking your 401(k), you can estimate doubling time without even reaching for your phone. If you need a super quick estimate and your rate divides evenly into 70, like 7% or 14%, then go with the rule of 70.
Compounded Interest vs. Continuous Compounding
Most investments you’ll actually use compound interest at set intervals. Your retirement account compounds yearly or quarterly.
Bonds pay at regular times. So, the rule of 72 usually fits best for financial planning.
Continuous compounding means interest gets added nonstop—honestly, you’ll barely run into this outside of theory or niche financial products. The rule of 70 started out for continuous compounding since it matches the math more closely. Unless your investment specifically says it uses continuous compounding, you’re almost always dealing with standard compounding.
If your investment compounds monthly or quarterly, the rule of 72 still gets you close enough. For example, a CD at 6% compounded monthly will double in about 12 years (72 ÷ 6), which lines up with the actual math for most planning purposes.
Using the Rules for Retirement Savings

Your retirement timeline really decides which rule matters more. If you’re 30 and have $50,000 in your 401(k) earning 7% a year, the rule of 72 shows your money hits $100,000 in about 10.3 years, $200,000 by age 50, and $400,000 by 61.
This quick math gives you a reality check without logging into every account or building a monster spreadsheet. You can tweak your contributions based on real doubling patterns, not just vague retirement dreams.
If you’re 55 and looking to retire at 65, the difference between your money doubling in 10 or 10.3 years won’t change your plan much. You’ll want to focus on where your money sits and how risky your portfolio is.
Younger investors with 30+ years until retirement should use the rule of 72 to map out investment growth at different savings rates. If you put $6,000 a year into a Roth IRA at 8% returns, you can estimate your balance at different ages by counting doubling periods. It really shows why starting early packs such a punch compared to waiting even a few years.
See Related: Frugal Living: Top Tips for Saving Money and Managing Finances
Practical Applications and Money-Saving Strategies
The Rule of 70 and Rule of 72 aren’t just math tricks—they help you see how inflation eats away your buying power, how fast an economy grows, and whether your budget tools actually help your money work for you.
Estimating GDP and Economic Growth

Economists use the Rule of 70 to make sense of GDP growth rates that seem tiny but add up over time. A country growing at 3.5% a year doubles its economy in 20 years (70 ÷ 3.5). That’s not just trivia—it affects jobs, wages, and whether your salary keeps up with the world around you.
If your region’s economy grows at 2%, doubling takes 35 years. That means your retirement savings need to work harder, since you can’t count on big raises to make up for bad saving habits.
You can use this logic for your career too. If you boost your income by 10% each year—whether through raises, side gigs, or learning new skills—you’ll double your earnings every 7.2 years (72 ÷ 10). That’s how you go from $50,000 to $100,000, not by hoping for a windfall.
Understanding the Impact of Inflation

Inflation quietly erodes your buying power, and the Rule of 72 shows how fast it happens. At 3% inflation, your money loses half its value in 24 years (72 ÷ 3). At 6%, it’s just 12 years.
That’s why keeping cash under your mattress—or even in a savings account earning 0.5%—actually costs you. If inflation’s at 3%, you’re losing 2.5% of your purchasing power each year. Your $10,000 emergency fund only buys $9,750 worth of stuff next year.
To see how quickly inflation halves your money, divide 72 by the inflation rate. When inflation spiked to 8% in 2022-2023, your costs were set to double in just 9 years. No wonder groceries suddenly felt so expensive.
The best defense? Invest in things that outpace inflation. If you earn 7% while inflation is 3%, you’re growing your real wealth by about 4% a year.
Integrating the Rules Into Budgeting Tools

Most budgeting apps don’t show you compound growth by default, but you can add it in. When you’re weighing paying off a 6% student loan versus investing in a retirement account at 8%, the Rule of 72 makes the tradeoff obvious. Your debt doubles in 12 years; your investment doubles in 9.
Set up a simple spreadsheet with three columns: financial goal, growth or interest rate, and doubling time. Update it every few months. If your savings account drops from 5% to 3%, your doubling time jumps from 14.4 to 24 years—a clear sign to look for better rates.
Thinking about refinancing your mortgage? Use the Rule of 72 on your old and new rates. Dropping from 6% to 4% means your interest cost structure goes from doubling in 12 years to 18, which frees up cash for other goals. Make this a habit before paying those refinancing fees.
Common Pitfalls and How to Get the Most Accurate Estimate
Both rules give you a ballpark, not a guarantee. Your actual results will change based on interest rates, investment fees, and taxes.
Variable Rates and Real-World Adjustments
Your investment won’t pull in 7% every year like clockwork. Markets swing up and down. Some years you might see 12%, others 2%, and sometimes you’ll even lose money.
The Rule of 72 and Rule of 70 both assume a fixed rate the entire time. If you use 6%, you get 12 years (72 ÷ 6). But if your returns bounce between 4% and 8%, your money could take 13 or 14 years instead.
A rule of 70 calculator or spreadsheet lets you test different scenarios. Plug in your best, worst, and average returns. For a stock-heavy portfolio, you might use 8-10% as your long-term average, but remember that’s just an average with lots of ups and downs.
If you’re looking at GDP or economic growth rates under 5%, the Rule of 70 gives a slightly better estimate. For your own investments with higher returns, stick with the Rule of 72.
Fees, Taxes, and Other Hidden Factors

A 7% return sounds solid until your mutual fund takes a 1% fee. Now you’re really earning 6%, and your doubling time stretches from 10.3 to 12 years.
Taxes take a bigger bite than most people expect. If your investment sits in a taxable account, you’ll pay on dividends and capital gains. A 7% return can drop to 5-5.5% after taxes, bumping your doubling time up to 13 or 14 years.
Inflation is always lurking. Your money might double in 10 years, but with 3% inflation, your real purchasing power only grows about 4% a year.
Watch out for these hidden costs:
- Fund expense ratios (anywhere from 0.05% to 2%+)
- Trading commissions
- Tax drag (which could be 15-37% depending on your bracket)
- Inflation (usually 2-3% per year)
It’s smarter to base your calculations on after-fee, after-tax returns.
Tips for Using Calculators and Spreadsheets

A basic rule of 70 calculator spits out one number, but spreadsheets let you model real life with changing rates each year. Set up Excel or Google Sheets with your starting balance, then add rows for each year’s returns.
Track your starting balance, annual return, fees, taxes, and ending balance. Copy the formula down for 20-30 years and see how small differences in rates or fees really add up.
For more precise math, use the natural logarithm formula: years to double = ln(2) / ln(1 + rate). At 6%, that’s ln(2) / ln(1.06) = 11.9 years.
The Rule of 72 says 12 years—pretty close. But at 15%, the Rule of 72 gives 4.8 years, while the actual answer is 4.96.
Test your spreadsheet with your own past returns. Grab your account statements from the last 5-10 years and see how close the rules came. It’s a good way to set realistic expectations for the future.
See Related: How to Manage Your Money with Personal Finance Software
Frequently Asked Questions
Both rules help you estimate how long it takes for investments to double, but they use different numbers and work best in different scenarios. Knowing when to use each one can make your financial decisions a bit sharper.
How does the Rule of 72 differ from the Rule of 70 in terms of estimating investment growth?
The main difference is the number you divide by your annual growth rate. With the Rule of 72, you divide 72 by your interest rate. With the Rule of 70, you divide 70 by your interest rate.
The Rule of 72 gives you a slightly longer estimate for doubling time. If you have a 9% return, the Rule of 72 says 8 years (72 ÷ 9), while the Rule of 70 says 7.8 years (70 ÷ 9). That 0.2 year gap may seem tiny, but when you’re planning for retirement decades out, it adds up.
The Rule of 72 tends to work better for typical investment returns between 6% and 10%. Most index funds, retirement accounts, and diversified portfolios fall here. The Rule of 70 feels a bit simpler in your head and works well for lower growth rates under 10%, like bonds or high-yield savings accounts.
Can you provide an example to illustrate how the Rule of 70 is used in calculating the time for an investment to double?
Let’s say you drop $5,000 into a bond fund and it earns 7% per year. You’re curious—when will that $5,000 turn into $10,000?
Just divide 70 by 7. You get 10 years. So, in about a decade, your investment should double if the rate holds steady.
Here’s another one. You invest $15,000 at a 5% annual return. The Rule of 70 says 70 divided by 5 is 14 years.
Your money grows to $30,000 in about 14 years. This quick trick helps you figure out if that growth rate feels good enough, or maybe you want to hunt for better returns.
What are the practical applications of the Rule of 72 when considering the impact of inflation on savings?
The Rule of 72 honestly makes it easy to see how fast inflation chews up your purchasing power. If inflation is running at 3%, just divide 72 by 3.
That’s 24 years. Your money’s value drops by half every 24 years if you’re not earning any returns.
It gets a bit nerve-wracking when inflation jumps. At 6%, your purchasing power halves in just 12 years (72 ÷ 6).
Imagine you keep $20,000 in a checking account that earns nothing. In 12 years of 6% inflation, that same $20,000 only buys what $10,000 does today.
You’ve got to compare your investment returns to inflation. If your savings account pays 2% but inflation is 4%, you’re losing 2% in real value every year.
The Rule of 72 makes this obvious. Divide 72 by 2—the difference—and your money’s value halves every 36 years. That’s why keeping too much cash might feel safe, but it quietly costs you over time.
Is there a situation where the Rule of 70 may be more accurate than the Rule of 72, and if so, could you explain it?
The Rule of 70 actually gives you closer estimates when you’re dealing with continuous compounding or really low growth rates. Think about population growth, some economic growth numbers, or savings accounts with daily compounding under 5%.
Let’s say your high-yield savings account pays 3.5% compounded daily. The Rule of 70 nails it better. Seventy divided by 3.5 is 20 years, which lines up with the true doubling time more closely than the Rule of 72.
For rates under 5%, the Rule of 70 just tends to be a bit more precise. But honestly, the difference is pretty minor.
If you’re doing quick math at the store or explaining compound growth to your teenager, either rule works. The main thing is just realizing how powerful compound growth gets over time.
In terms of retirement planning, how can the Rule of 72 help in determining the growth of a retirement fund?
The Rule of 72 really helps you set some real expectations for your retirement savings. If your 401(k) averages 8% returns, just divide 72 by 8.
That’s 9 years. Every $10,000 you save turns into $20,000 in 9 years, $40,000 in 18, and $80,000 in 27.
Let’s look at a real example. If you’re 35 and have $50,000 in your retirement account earning 8%, by 44 you’ll have around $100,000.
By 53, that grows to $200,000. By retirement at 62, you’re looking at $400,000—even if you never add another dime.
This is why starting early makes such a difference. If a 25-year-old puts in just $10,000 at 8%, that money doubles four times by age 61, turning into $160,000.
If you wait until 45 to invest the same $10,000, it might only double once or twice before retirement. The Rule of 72 lays out these timeframes, making it a lot easier to plan your contributions.
Are there any circumstances where the Rule of 70 or the Rule of 72 might not be the best tools to use for financial projections?
Honestly, both rules kind of break down when your returns jump around every year. Most investments don’t behave in a straight line.
Maybe your stocks shoot up 15% one year, then drop 8% the next. These rules just assume everything grows at a smooth, steady rate. So, you only get a ballpark estimate, not a real prediction.
Things get even messier at the extremes. If you’re looking at growth rates over 20% or under 2%, the math just doesn’t hold up.
Let’s say a startup claims it’ll grow at 30% per year, or your bank offers 0.5% interest—these rules just won’t track reality. You’ll want to use an actual compound interest calculator for those.
And honestly, don’t bother with these shortcuts for short-term decisions. Trying to decide whether to pay off a credit card at 18% interest or invest for just six months? You’ll need real numbers, not a quick mental trick.
Leave a Reply